
Liquid Ammonia CAS: 166412-78-8
Liquid Ammonia CAS: 166412-78-8
War-risk insurance premiums surged by around 50% during the earlier Gulf disruption, increasing logistics costs for chemical shipments. Procurement and compliance teams should understand how insurance pricing and regulatory oversight can influence sourcing decisions and freight budgets.
The upcoming VCI Q2 2026 report underscores a sharp decline in German chemical production, driven by soaring feedstock costs and weak domestic demand. Naphtha‑based downstream plants are hit hardest, while export disruptions to Asia and the Gulf further strain utilization rates. For buyers, the data offers critical insight into supplier stability and pricing dynamics across Europe.
Gulf caustic soda supply is returning as Hormuz trade flows recover, creating new competition for Asian chemical suppliers. This analysis explains how buyers can prepare for changing pricing and sourcing options in Q3 2026.
The nylon 6 supply chain faces renewed pressure after LEUNA-Polyamid entered insolvency proceedings, creating uncertainty for European caprolactam production. Buyers should reassess sourcing strategies as specialty chemical capacity remains under pressure.
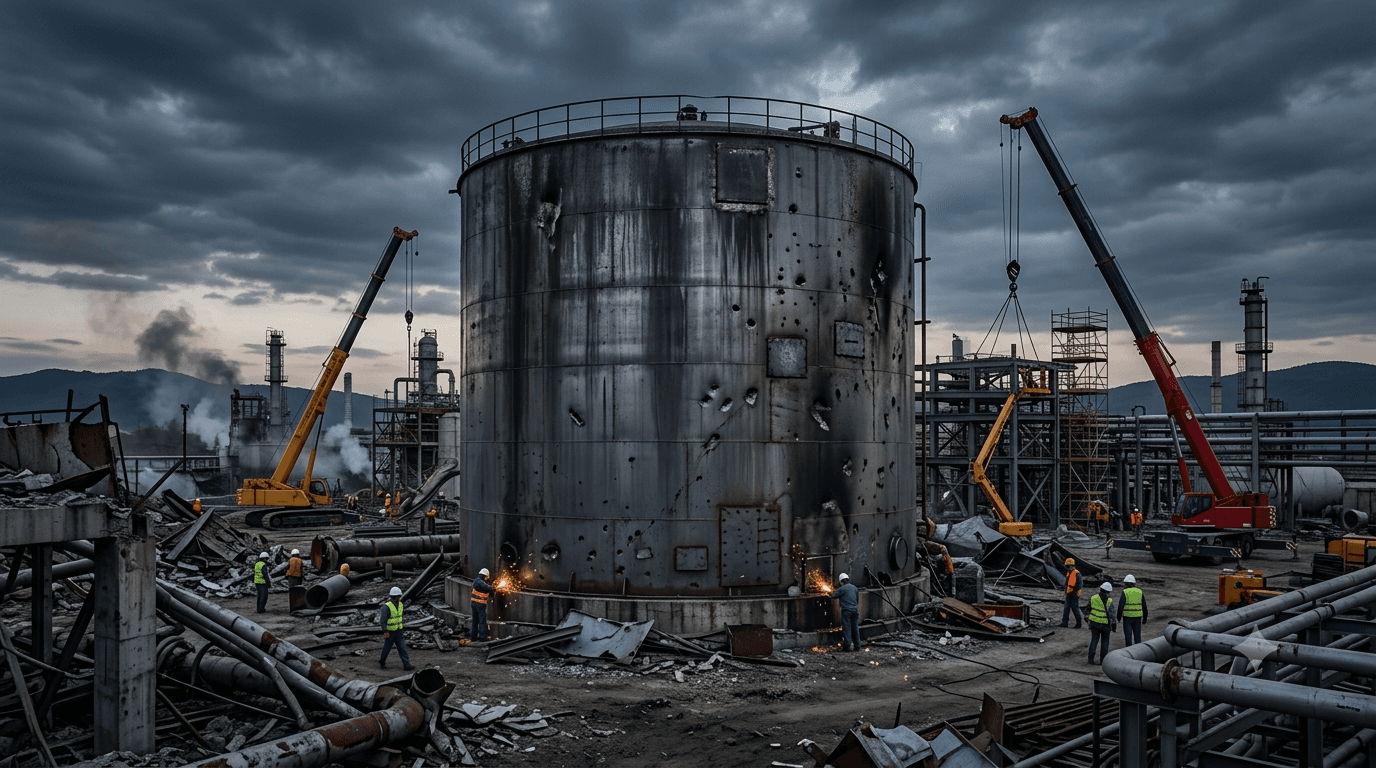
Iran’s petrochemical industry emerged as the largest industrial casualty of the Hormuz War, with major production hubs reportedly suffering catastrophic damage. The resulting supply gap is reshaping methanol, fertilizer and polymer markets while creating one of the largest reconstruction opportunities in the global chemical sector.
India's integrated sorbitol production capacity is strengthening its position as a reliable alternative sourcing destination.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.