Polypropylene prices have reached levels that many buyers had not expected to see during 2026. Limited propylene availability, reduced operating rates at Chinese PDH plants and supply disruptions across the Gulf pushed the regional PP market to four year highs. That market balance now shows clear signs of changing.
Polypropylene enters the second half of the year with improving feedstock availability as Gulf LPG exports gradually recover. Chinese PDH operators can once again secure propane cargoes, allowing production rates to increase through July. Procurement teams should monitor this transition closely because today's tight market could shift toward greater supply and lower prices by August.
Why Chinese PDH Units Matter to the Polypropylene Market
China operates one of the world's largest fleets of propane dehydrogenation plants. Unlike steam crackers that produce several petrochemicals simultaneously, PDH facilities primarily convert propane into propylene, which then serves as the main building block for polypropylene.
When propane supplies become scarce, PDH operators quickly reduce production because feedstock represents the largest share of operating costs. Lower propylene output immediately tightens PP supply and supports higher resin prices throughout Asia.
The opposite also applies. As propane availability improves, PDH plants increase operating rates, propylene inventories rebuild and downstream polypropylene producers gain access to more competitively priced raw materials.
Gulf LPG Recovery Changes the Supply Outlook
The recent recovery in LPG exports from major Gulf suppliers marks an important turning point for Asian petrochemical markets.
Countries such as Qatar, the UAE and Kuwait have gradually restored export capacity after severe logistical disruptions earlier in the year. Current shipping volumes remain below historical averages but have climbed to roughly 75 percent of pre-war capacity.
That increase provides Chinese buyers with significantly better access to propane cargoes compared with the previous month.
Several immediate market effects have emerged:
• PDH operators can improve plant utilization without competing aggressively for every available cargo.
• Propane premiums may gradually ease as additional export volumes enter Asian markets.
• Propylene production is likely to recover steadily during July rather than through sudden capacity additions.
• Downstream polypropylene producers gain greater confidence when planning production schedules for August and September.
These developments reduce one of the strongest bullish drivers that supported PP prices during the previous quarter.
How the PP Price Correction Could Develop
Market corrections rarely happen overnight. Instead, they usually follow a sequence of events that gradually changes supply and demand expectations.
The expected progression for the current market includes several stages.
First, additional LPG cargoes reach Chinese import terminals.
Next, PDH facilities restart previously idle units or increase utilization rates.
Propylene inventories then begin rebuilding across the domestic market.
As propylene becomes more available, polypropylene production increases while margins begin to narrow.
Finally, higher resin availability creates greater competition among suppliers, placing downward pressure on spot prices.
If this sequence continues without significant disruption, August could become the first month where buyers experience meaningful PP price corrections following the extended rally.
Propylene Inventory Growth Will Pressure Producer Margins
Many polypropylene producers have benefited from exceptionally strong margins while feedstock shortages restricted market supply.
That pricing environment becomes much harder to maintain once propylene availability improves.
Higher inventories generally reduce urgency among buyers. Producers compete more aggressively for sales, distributors rebuild warehouse stocks and contract negotiations shift toward customer leverage rather than supplier leverage.
Margin compression often arrives before finished resin prices fall sharply. This transition represents one of the strongest indicators that procurement teams should monitor throughout July.
The Trade Flow Picture Across Asia
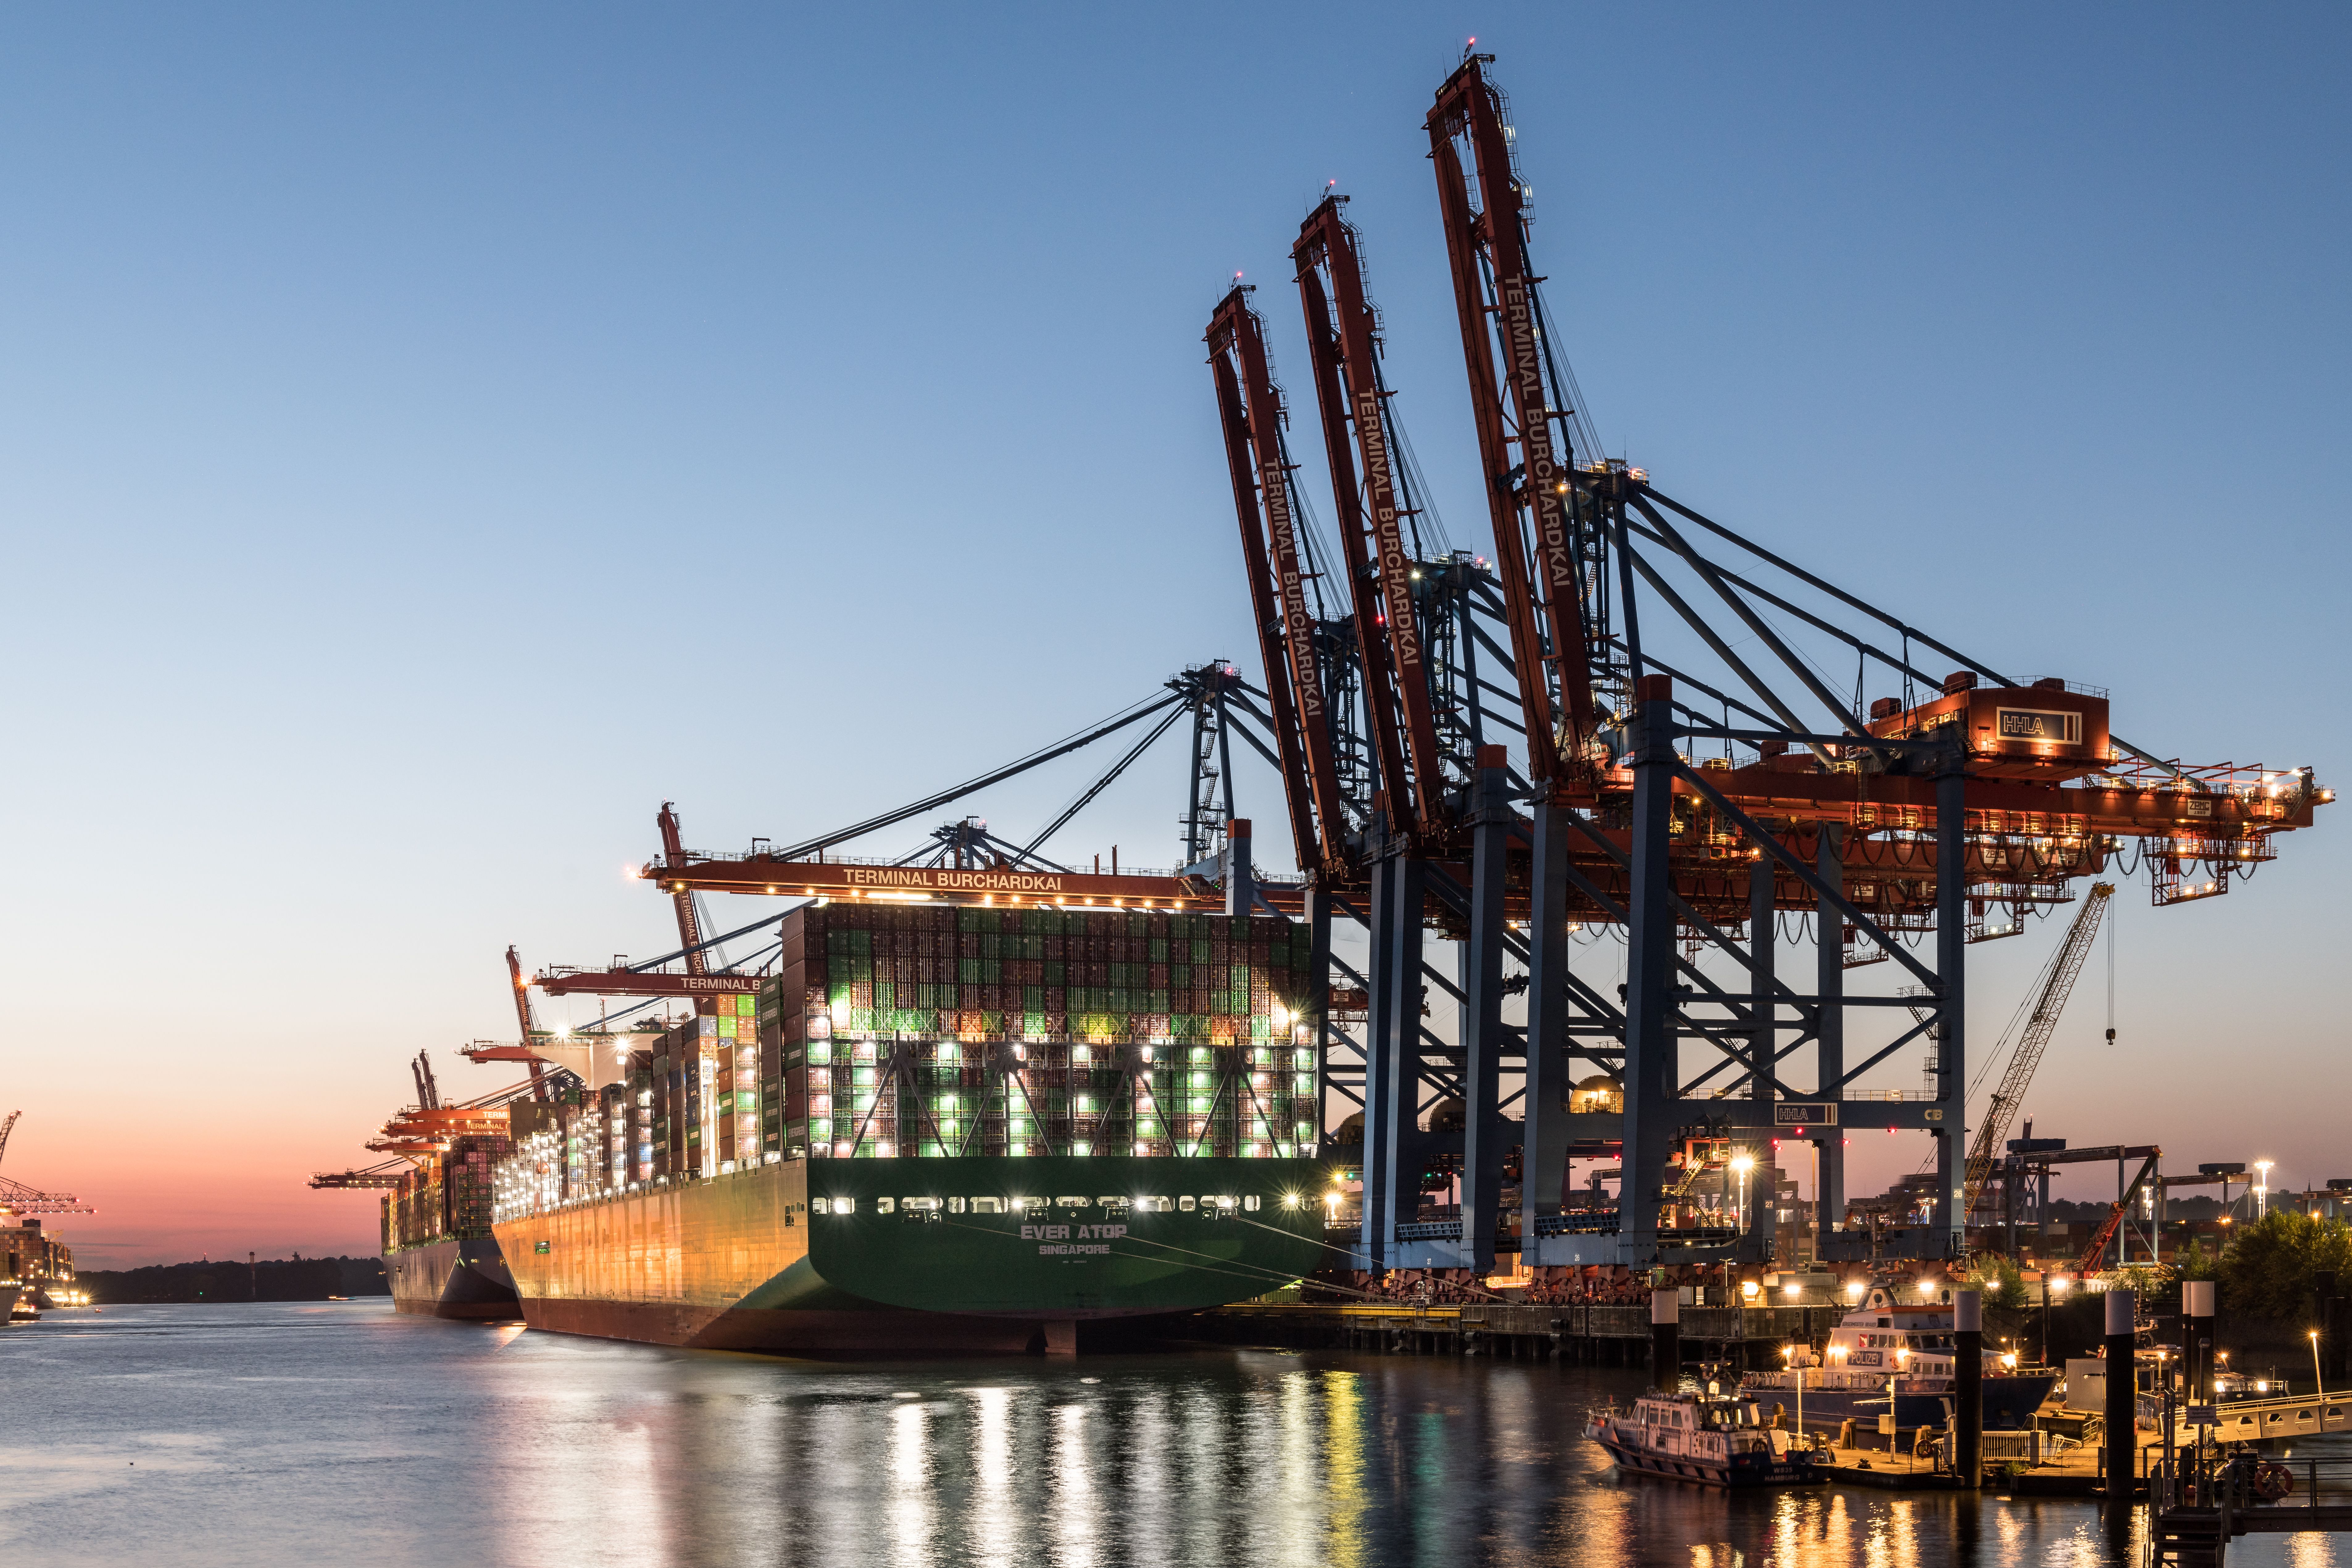
Asian polypropylene trade flows are entering a period of realignment. During the supply disruption, buyers competed for limited cargoes while producers prioritized markets offering the strongest margins. As additional PP volumes enter the market, those trade patterns will gradually normalize.
Chinese producers are likely to increase domestic sales first as inventories recover. Once supply becomes more comfortable, exporters may return to regional markets with more competitive offers. This shift could increase pricing pressure across Southeast Asia and parts of South Asia.
Importers should also watch freight availability. Better feedstock supply alone does not guarantee lower delivered costs if shipping rates rise or vessel availability tightens during the quarter.
Indian Buyers Face a Unique Pricing Challenge
India enters this market transition under very different conditions than China.
While Chinese buyers benefit from improving feedstock availability and increasing domestic production, Indian importers face the possibility of renewed import duties after the expiration of temporary relief measures. This creates two competing pricing forces that procurement teams must evaluate carefully.
One scenario favors buyers if falling Chinese and Gulf polypropylene prices offset the additional import costs. The second scenario creates a more balanced outcome where lower international prices only partially compensate for higher duties.
For procurement managers, this means landed cost calculations become more important than headline PP prices.
Key variables include:
International polypropylene offers may soften through August as additional supply reaches the market. Buyers should compare multiple origins before committing to large purchases.
Import duty changes could increase final procurement costs despite lower resin prices. Each shipment should be evaluated using updated landed cost calculations.
Freight charges remain an important variable. Lower product prices can quickly lose their advantage if transportation costs increase unexpectedly.
Exchange rate movements may further influence purchasing decisions for companies importing large monthly volumes.
Companies that model these factors together will make stronger purchasing decisions than those focusing only on spot market quotations.
Industries Most Likely to Benefit
A softer polypropylene market supports several downstream manufacturing sectors that rely on stable resin costs.
Packaging manufacturers typically respond quickly because polypropylene represents a significant portion of their raw material spending. Lower resin prices improve production economics and create opportunities to rebuild inventory.
Other industries that may benefit include:
Automotive component manufacturers, where polypropylene supports lightweight interior and exterior parts.
Consumer goods producers that manufacture household products, storage containers and molded accessories.
Textile manufacturers using polypropylene fibers for industrial fabrics and woven products.
Pipe and construction material producers that depend on consistent resin supply for long production runs.
Medical and food packaging companies that require reliable availability of high quality polypropylene grades.
These sectors often increase purchasing activity once they gain confidence that prices have stabilized.
Procurement Strategies for the Third Quarter
Market transitions reward disciplined procurement rather than reactive purchasing.
Companies that rushed to secure material during supply shortages may now have greater flexibility, but that does not mean delaying every purchase. Supply conditions continue to improve, yet unexpected geopolitical developments or logistics disruptions could still interrupt the recovery.
Procurement teams should consider several practical actions:
Monitor Chinese PDH operating rates each week because higher utilization generally signals additional propylene production ahead.
Compare offers from Gulf, Chinese and other Asian suppliers rather than relying on existing sourcing channels.
Balance spot purchases with contract commitments to reduce exposure to sudden market swings.
Review warehouse inventory levels before making large procurement decisions. Excess inventory purchased at peak prices could affect profitability during a declining market.
Maintain close communication with logistics providers to identify changes in freight costs or shipping schedules.
A flexible purchasing strategy often delivers better results than attempting to predict the exact bottom of the market.
Risks That Could Delay the Expected Price Correction
Although current indicators support a softer polypropylene market, several risks could slow or even reverse the expected correction.
Additional disruptions to Gulf LPG exports remain the largest concern. Any interruption to propane supply would immediately affect Chinese PDH operating rates and reduce propylene availability once again.
Unexpected production outages at major polypropylene plants could also tighten regional supply despite improving feedstock conditions.
Demand presents another important variable. If manufacturing activity strengthens more rapidly than expected across Asia, additional polypropylene consumption could absorb the new production without creating significant inventory growth.
Currency volatility, freight market disruptions and changes in energy prices also deserve close attention because they directly influence production costs and international trade competitiveness.
For these reasons, procurement teams should treat the current forecast as a high probability scenario, not a guaranteed outcome.
What Buyers Should Do Now
The polypropylene market appears ready to move from a period of scarcity toward a more balanced supply environment. Recovering LPG exports from Gulf producers support higher operating rates at Chinese PDH facilities, increasing propylene availability and placing downward pressure on polypropylene prices through the third quarter.
August could become the first meaningful correction after months of elevated pricing if production continues recovering as expected. Buyers who combine market intelligence with disciplined procurement planning will be better positioned to benefit from changing conditions while managing the remaining supply risks.
For Indian importers, the coming weeks deserve particular attention because international price declines and changing import duties may offset each other. Careful landed cost analysis, diversified sourcing and timely purchasing decisions will provide the strongest competitive advantage as the market adjusts.
Ready to source polypropylene from verified global suppliers? Explore competitive offers on our platform today.
Propylene Oxide CAS: 75-56-9