The PTA and paraxylene value chain entered the second half of 2026 with one question dominating procurement discussions: will the Hormuz ceasefire meaningfully restore supply before Q3 contracts are finalized?
PTA and paraxylene prices climbed sharply during the Hormuz disruption as buyers rushed to secure material while supply risks intensified across the Gulf region. Now, with a memorandum of understanding signed on June 19, 2026, market participants face a different challenge. They must determine whether current elevated pricing reflects a temporary disruption or a new baseline for Q3 negotiations.
For polyester producers, traders and importers, the timing could not be more important. PTA and PX remain critical feedstocks for textile fibers, PET packaging and a wide range of industrial applications throughout Asia.
Why PTA and Paraxylene Remain Central to the Polyester Chain
Purified terephthalic acid (PTA) and paraxylene (PX) sit at the heart of the global polyester industry.
Paraxylene serves as the primary upstream feedstock for PTA production. Producers then combine PTA with monoethylene glycol to manufacture polyester resins and fibers used across multiple industries.
Demand remains strong because these materials support:
Polyester textile production, which remains one of Asia's largest manufacturing sectors.
PET bottle manufacturing for food, beverage and consumer goods packaging.
Industrial yarns and specialty fibers used in automotive and construction applications.
Film and packaging products that require durability and cost efficiency.
When PX supply tightens, the impact quickly spreads throughout the entire polyester chain.
How the Hormuz Crisis Disrupted PTA and PX Supply
The Hormuz disruption affected one of the world's most important petrochemical corridors.
Iran, the UAE and Qatar contribute substantial volumes of paraxylene and PTA to regional and international markets. Shipping uncertainty, vessel rerouting and risk premiums created immediate pressure on buyers dependent on Gulf-origin cargoes.
Chinese PTA producers felt the impact particularly strongly.
Many facilities rely on imported PX feedstock from Gulf suppliers. As cargo flows became less predictable, several operators reduced utilization rates to preserve feedstock inventories and manage operational risk.
At the same time, freight costs increased significantly.
Importers faced higher transportation expenses, longer delivery schedules and reduced spot availability. These factors pushed market sentiment higher even before physical shortages emerged in some regions.
The result was a market driven as much by uncertainty as by actual supply deficits.
Chinese Refinery Expansion Changes the Supply Equation
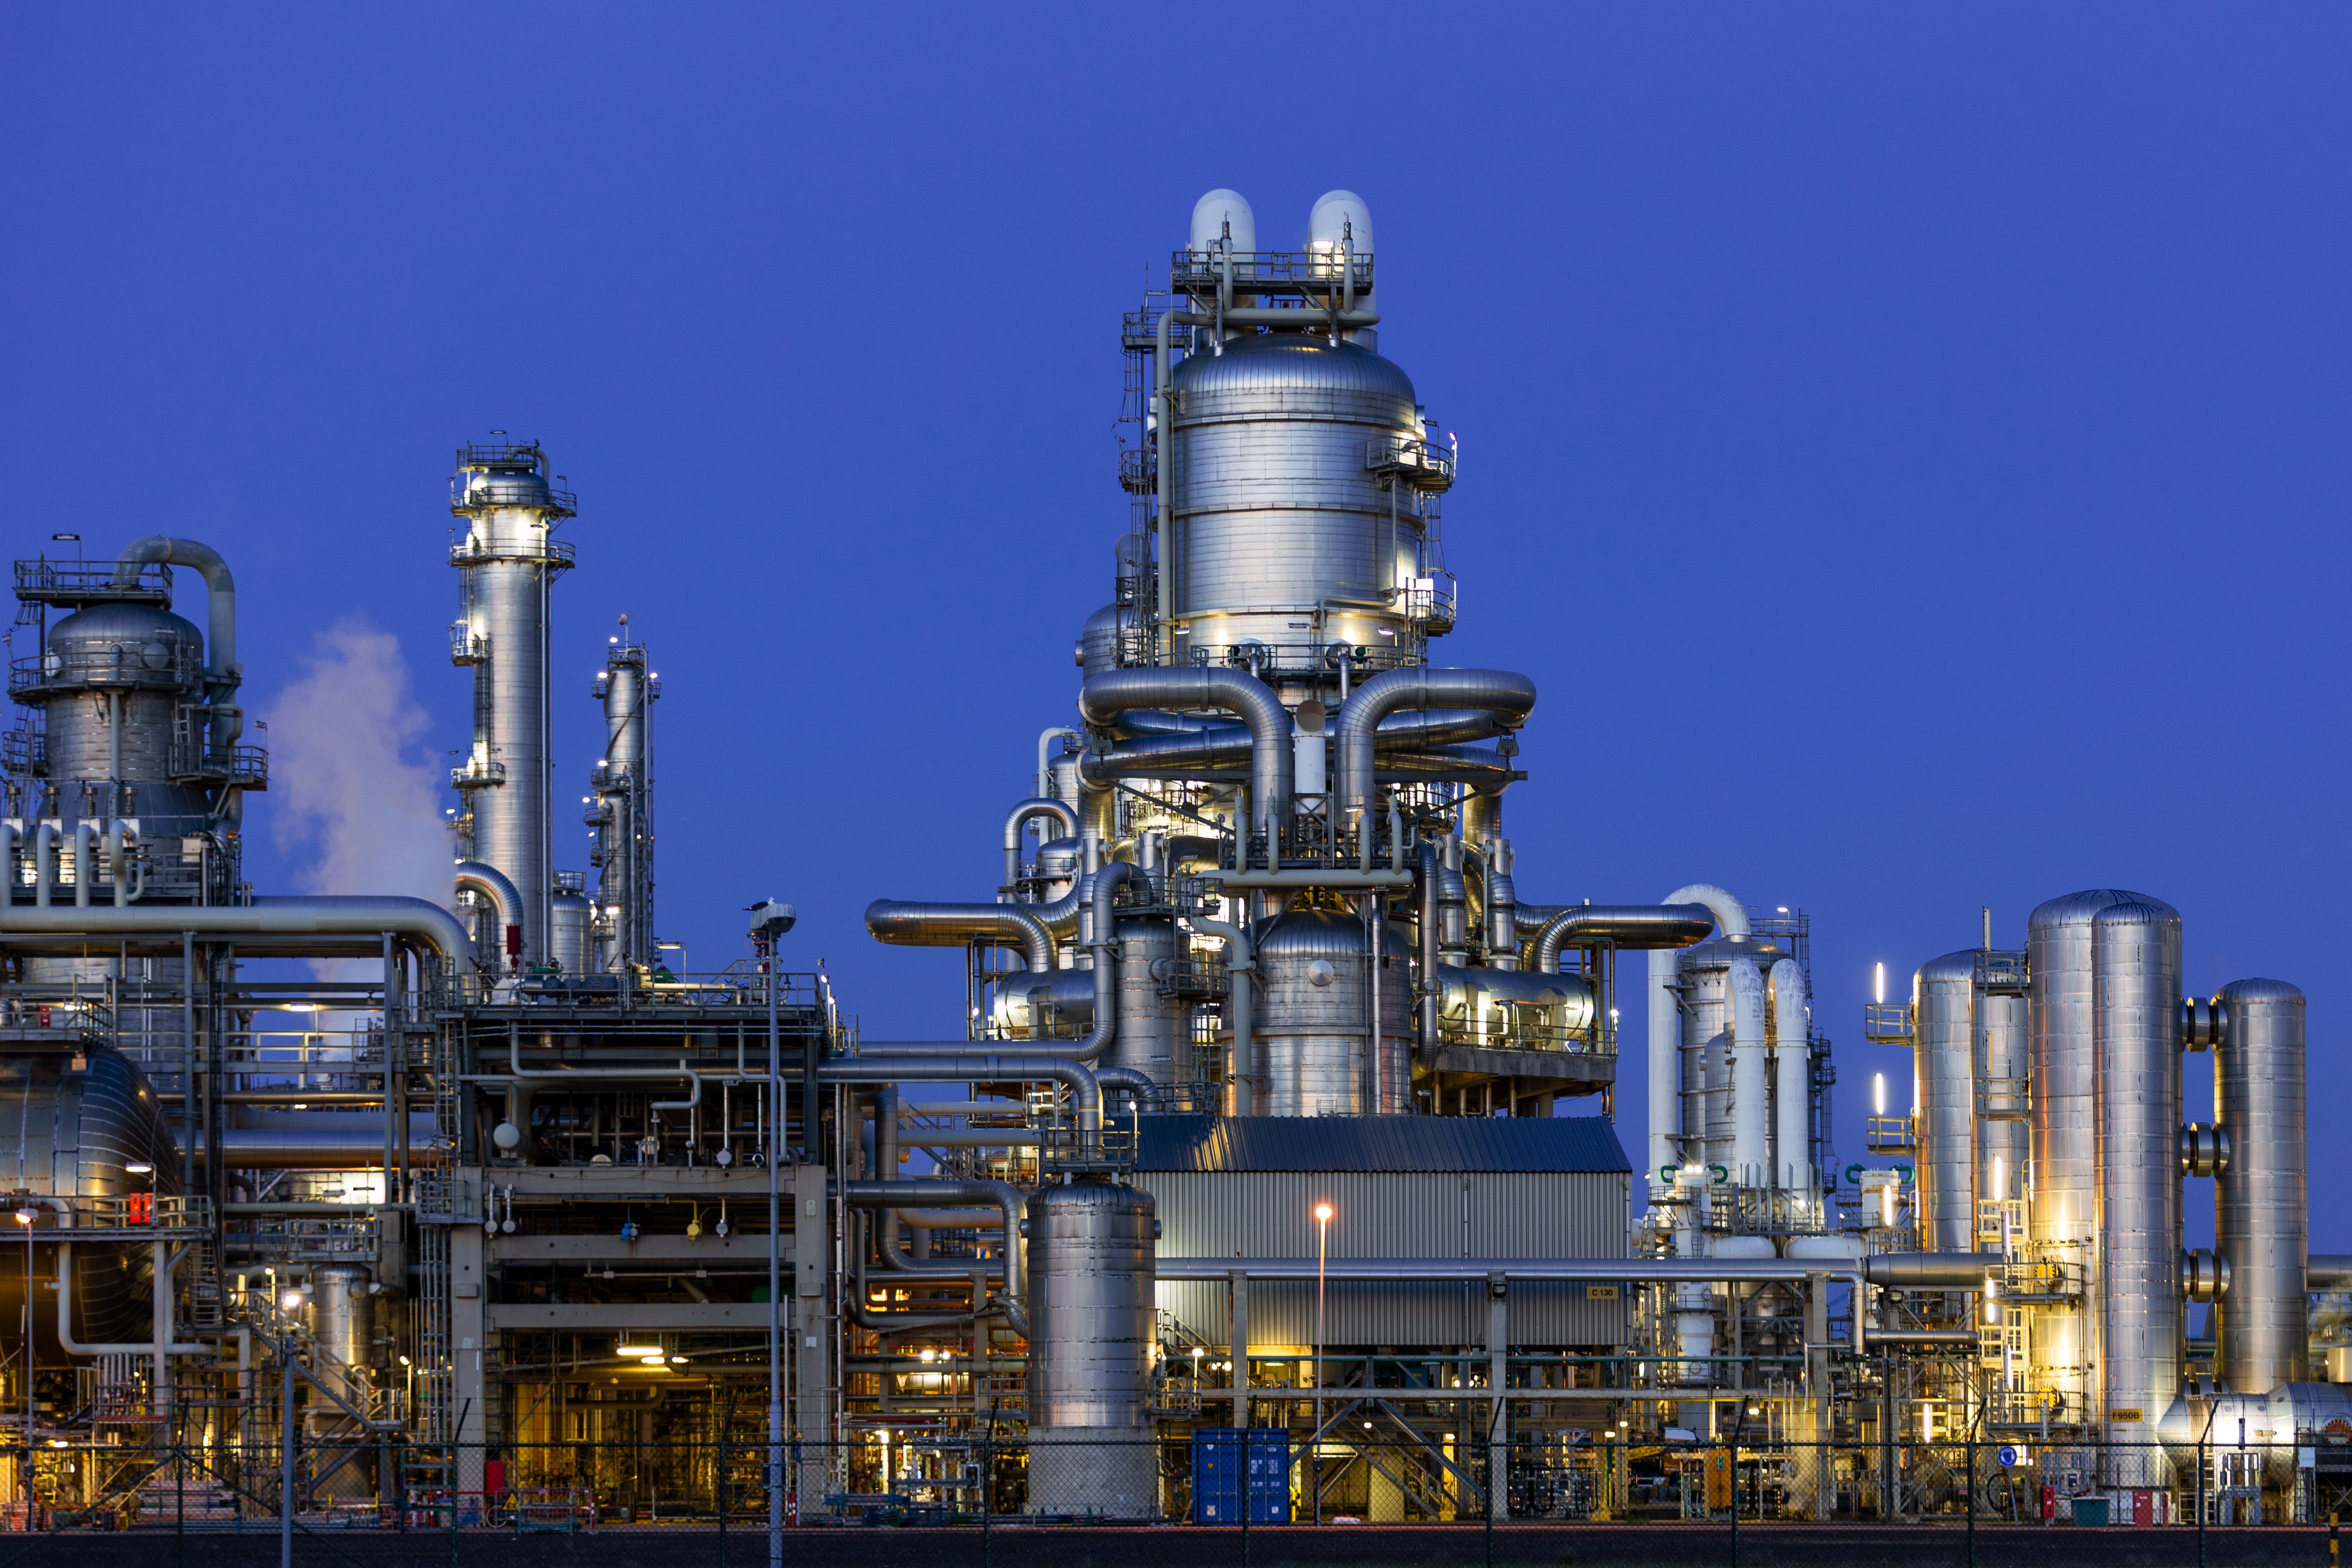
The current market differs from previous supply disruptions because China has expanded domestic refining and aromatics capacity over recent years.
Additional domestic PX production has helped offset part of the feedstock shortage that emerged during the crisis. This internal supply cushion prevented a more severe disruption across the polyester value chain.
However, domestic production has not fully replaced imported volumes.
Several market participants continue to depend on imported PX because of established supply contracts, product specifications and regional logistics advantages.
This creates a mixed environment where some buyers enjoy greater flexibility while others remain exposed to import risks.
The key question for Q3 negotiations centers on how quickly imported Gulf volumes can return to normal trading patterns.
Q3 Contract Negotiations Face an Unusual Risk Balance
Contract discussions rarely occur under conditions where both bullish and bearish arguments carry equal weight.
Buyers considering immediate purchases can point to:
Current spot markets remain elevated compared with historical averages.
Freight costs continue to reflect recent disruptions.
Physical logistics recovery typically takes longer than political agreements.
Supply chains need time to rebuild inventories after periods of uncertainty.
Suppliers, meanwhile, can argue that:
Production capacity remains largely intact in several exporting regions.
The ceasefire framework may improve cargo movement during the coming months.
Market participants could reduce panic buying if confidence improves.
Additional regional production can gradually ease supply concerns.
Because both sides hold credible arguments, contract negotiations have become increasingly complex.
Indian PTA Importers Push for Extended Duty Relief
India represents one of the most important PTA-consuming markets in Asia.
The country's large polyester and textile industries depend on reliable feedstock availability to maintain production and export competitiveness.
As market volatility continues, Indian importers have sought extended duty relief measures to reduce procurement costs and improve supply security.
The reasoning is straightforward.
Lower import duties can help offset elevated raw material costs while supporting downstream industries that compete in international markets.
For procurement managers, any extension of duty relief could significantly influence purchasing strategies during the second half of 2026.
Regional Trade Flows Are Being Reassessed
The crisis encouraged buyers to reconsider traditional sourcing patterns.
Companies that historically concentrated purchases from a limited group of Gulf suppliers began evaluating broader procurement networks.
Several trends emerged:
Asian buyers increased discussions with alternative suppliers outside the Gulf region.
Traders explored more flexible logistics arrangements to reduce route concentration risk.
Importers reviewed inventory policies that previously prioritized lean stock levels.
Procurement teams placed greater emphasis on supplier diversification.
These shifts may continue even if supply conditions improve.
Risk management has become a larger component of purchasing decisions across the petrochemical sector.
What PTA Buyers Should Watch During the Next 60 Days
The next two months will provide critical signals regarding market direction.
Several indicators deserve close attention:
Shipping Activity
Buyers should monitor vessel movements and cargo availability from Gulf export hubs. Increased shipping activity would suggest improving supply confidence.
Freight Rates
Transportation costs often react faster than contract markets. Falling freight premiums could indicate normalization before it appears in PTA pricing.
PX Availability
Paraxylene supply remains one of the most important variables. Greater PX availability would support higher PTA operating rates across Asia.
Plant Operating Rates
Chinese PTA utilization levels provide a useful measure of market confidence. Rising operating rates would signal improved feedstock access.
Inventory Rebuilding
Producers and traders will likely rebuild inventories after recent disruptions. Inventory accumulation could temporarily support demand even if supply improves.
Procurement Strategies for Polyester and PET Producers
Procurement teams face a difficult balancing act.
Locking in volumes today provides supply certainty but may expose buyers to downside price risk if conditions improve rapidly.
Waiting for potential market softening creates opportunities for cost savings but increases exposure to supply disruptions if recovery progresses more slowly than expected.
Many buyers are adopting hybrid strategies.
These approaches often include:
Securing core requirements through contracted volumes.
Maintaining flexibility for additional spot purchases.
Diversifying supplier portfolios across multiple regions.
Monitoring logistics indicators alongside price trends.
Establishing contingency supply options before peak demand periods.
This strategy allows companies to balance cost control with supply security.
The Relationship Between PX and PTA Pricing
Understanding the connection between PX and PTA remains essential for effective procurement planning.
PTA pricing generally follows paraxylene fundamentals because PX represents a major production cost component.
When PX becomes scarce, PTA producers experience higher feedstock expenses. These costs typically move downstream through the value chain.
However, the relationship is not always immediate.
Factors such as inventory levels, operating rates, regional demand and freight costs can temporarily alter the pricing relationship between the two products.
During periods of market stress, procurement teams should monitor both markets rather than focusing exclusively on PTA prices.
Looking Ahead to the Second Half of 2026
The market now stands at a turning point.
The Hormuz ceasefire has reduced immediate fears regarding prolonged supply disruption. At the same time, logistics systems, freight markets and inventory positions require time to normalize.
This means volatility may continue even if the overall direction becomes more stable.
Buyers who assume an immediate return to pre-crisis conditions may underestimate the time needed for supply chains to recover fully.
Conversely, those expecting continued severe shortages could overlook the market's ability to adapt through alternative sourcing and increased regional production.
For Q3 negotiations, flexibility may prove more valuable than attempting to predict a single market outcome.
What Buyers Should Do Now
PTA and paraxylene procurement teams face one of the most challenging contracting environments of 2026. The combination of recovering supply, elevated pricing and uncertain logistics creates a market where timing matters as much as price.
The most effective buyers will focus on supply security, supplier diversification and continuous monitoring of freight, inventory and feedstock indicators. Companies that remain agile during the next 60 days will likely secure the strongest negotiating position as market conditions evolve. Ready to source Purified Terephthalic Acid from verified global suppliers? Explore competitive offers on our platform today.
Purified Terephthalic Acid CAS: 100-21-0