Introduction
In 2024 the National Development and Reform Commission (NDRC) announced a comprehensive decarbonization framework that prioritizes low‑carbon feedstock production. For China’s ethylene market, the policy signals a decisive shift toward greener crackers, with a projected impact on global pricing dynamics by 2026.
Policy Highlights
The NDRC mandate focuses on three core areas:
Feedstock Transition – Encourage natural gas and biogas feedstock over coal‑based processes.
Efficiency Standards – Set new energy‑intensity benchmarks for all new and upgraded crackers.
Carbon Pricing – Implement a carbon tax that rises annually, making high‑carbon pathways less economical.
Impact on China Crackers
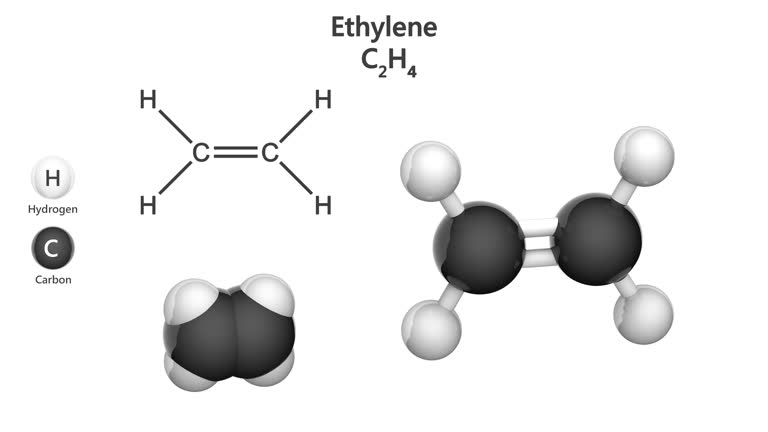
China’s ethylene producers are rapidly adjusting:
New crackers are being built with advanced steam methane reforming (SMR) technologies.
Existing plants are retrofitted with carbon capture and utilization (CCU) to meet stricter emissions limits.
Investment flows now favor low‑carbon feedstock suppliers, increasing their bargaining power.
Competitive Edge for Ethylene
The policy creates a cost advantage for domestically produced ethylene:
Lower operating costs due to cheaper natural gas prices in China’s hinterlands.
Reduced regulatory fines and compliance expenses for newer, cleaner facilities.
Access to preferential financing from state‑backed green funds.
Global Pricing Implications
By 2026, the ripple effects are expected to be noticeable on the world stage:
China’s increased ethylene output will tighten global supply, raising prices for petrochemical consumers.
European and North American markets may face higher feedstock costs, prompting a shift toward alternative plastic production routes.
Emerging economies may experience a price squeeze, potentially accelerating their own decarbonization efforts.
Strategic Recommendations
Stakeholders should consider the following actions:
Supply Chain Alignment – Secure long‑term natural gas contracts to hedge against price volatility.
Technology Partnerships – Collaborate with Chinese firms on CCU and renewable hydrogen projects.
Market Diversification – Explore downstream opportunities in high‑value polymer segments to offset raw material cost pressures.
PVC S65D-61518 (Ethylene based - SG 5) - Taiwan CAS: 9002-86-2
High Density Polyethylene (HDPE) CAS: 9002-88-4